Fort Myers Small Business Disaster Recovery Financial Checklist
A storm can close your shop in a day, but the bills may keep arriving for weeks. For a Fort Myers owner, small business disaster recovery starts with knowing what you own, what you owe, and how long your cash can cover essential costs.
You can prepare much of that information before hurricane season. If damage occurs, the same records help you document losses, contact your insurer, and make decisions without guessing.
Build a small business disaster recovery file before hurricane season
Keep a financial file you can reach even if your office loses power or floods. Review it each spring, then update it whenever you buy equipment, change insurers, or open a new account.
Save records that show income and obligations
Export recent tax returns, payroll reports, sales records, bank statements, loan agreements, and accounts receivable and payable reports. Keep supplier invoices and receipts for major purchases. If you collect Florida sales tax, retain the reports supporting your filings, too.
Reconcile bank and credit card accounts before saving reports. Otherwise, a cash balance or unpaid invoice list may mislead you when time is short. Small business bookkeeping in Fort Myers can help bring those records current before a storm threatens.
Store encrypted copies somewhere accessible away from the premises. Limit access to people who need it, especially when files contain employee or customer information. Keep a second way to reach critical records in case your usual internet connection fails.
Record what the business owns
Create an inventory of equipment, furniture, stock, and improvements to your leased space. For expensive items, capture serial numbers, purchase dates, invoices, and clear photos. Walk through the premises on video, including storage areas and mechanical equipment.
The IRS recommends preserving records that can help reconstruct assets, inventory, income, and expenses after a disaster. An inventory made before damage occurs gives you a more reliable starting point than memory alone.
If your books are in QuickBooks, check that bank feeds connect to the correct accounts and reconcile regularly. A feed can import transactions without categorizing them correctly. QuickBooks assistance in Fort Myers can help resolve setup or reconciliation problems before they complicate a claim.
Review coverage and contacts while you can still ask questions
A policy summary is useful, but the policy terms control what may be covered. Make time to review them before you need to file a claim.
Check the coverage that matters to your operation
Ask your insurance agent how your property, equipment, inventory, and any business interruption coverage apply. Check deductibles, limits, exclusions, waiting periods, and documentation requirements. Flood and wind damage may be treated differently, so don't assume one policy covers both.
If you rent, review your lease alongside your policy. Find out who is responsible for the building, your improvements, and damaged equipment. Write down the answers and keep the policy documents in your recovery file.
Keep an offline contact sheet
Save your insurer's claim number, policy number, landlord's contact details, bank and lender information, payroll provider, key suppliers, and accountant's contact details. Include a backup contact for the person authorized to approve payments if you're unavailable.
Lee County emergency information can guide safety decisions and evacuation planning. Your financial contact sheet has a different job: helping you reach the people who can keep payroll, claims, and essential payments moving once everyone is safe.
Make a cash plan for an interruption
A profitable month doesn't guarantee enough cash for a closure. Customer payments may slow while payroll, loan payments, and storm preparation costs continue.
Forecast bills against cash you can access
List available cash and expected collections by week. Then add payroll, rent, insurance, debt payments, taxes, and essential vendor bills by due date. Run the forecast for several weeks beyond a possible closure, since reopening doesn't mean customers pay immediately.
Review overdue invoices before a storm. Follow up on valid balances and resolve disputes while your records are easy to reach. During strong sales periods, revisit your cash reserve rather than treating the full bank balance as available to spend.
Decide what can wait
Identify expenses you could pause without putting employees, property, or critical services at risk. Know which vendors require prompt payment and which lenders may discuss options if operations stop. Ask before a payment is late ; don't assume a deferral is available.
Keep an up-to-date balance sheet and profit and loss statement with your forecast. They show obligations and operating results that a bank balance can't. If reports disagree with bank activity, financial statements for small businesses can help establish a sound starting point.
After a disaster, document damage before records disappear
Put personal safety and official access restrictions first. When you can safely enter the premises, begin a dated record of conditions and decisions.
Photograph, list, and report the loss
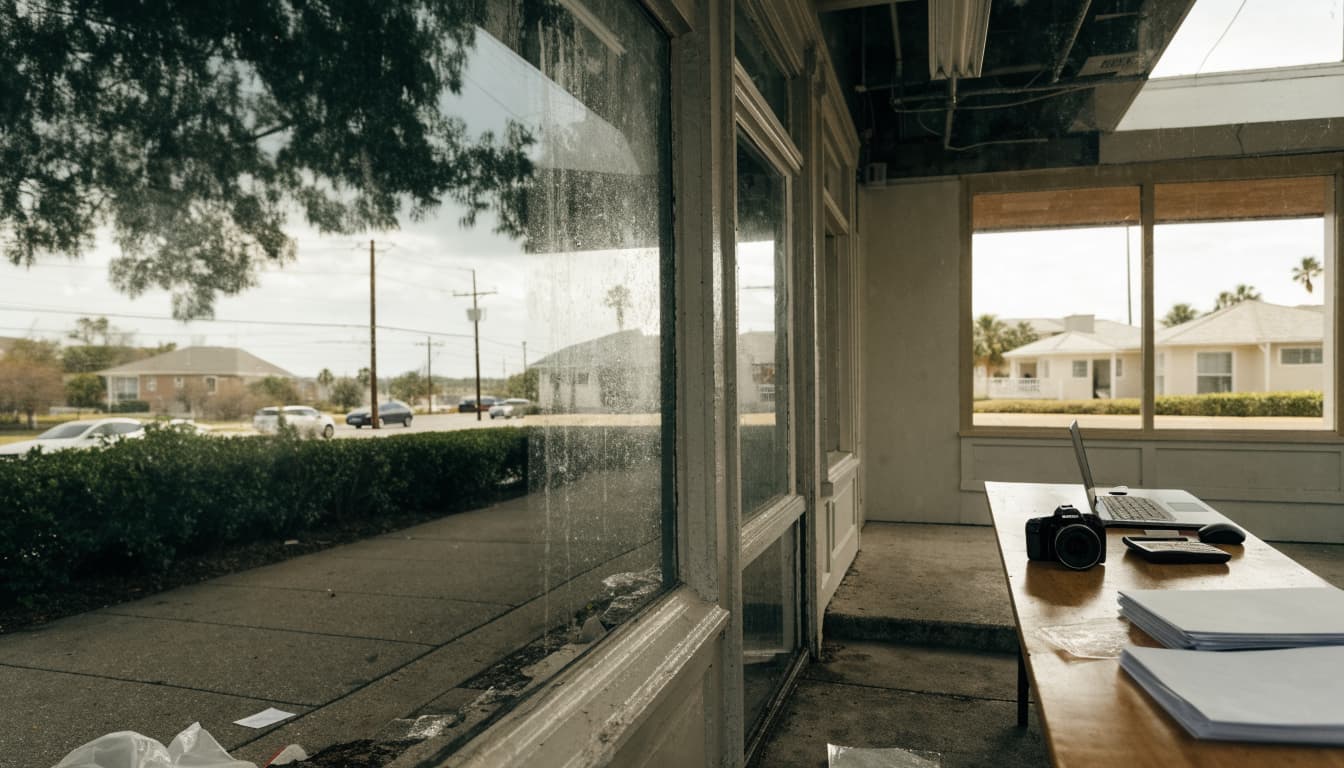
Take wide photos of each affected area, then close-ups of damaged items. Note model numbers and match purchases to invoices where possible. Record when you discovered damage, whom you contacted, and any instructions your insurer gave.
Notify your insurer promptly and follow its claim process. Ask how to handle damaged property before disposing of it, while taking reasonable steps to prevent further damage when safe. Keep copies of estimates, adjuster communications, and payments. Filing a claim does not guarantee a particular reimbursement.
If original tax records are lost, an accountant can help identify documents to request again. IRS Form 4506-T requests certain tax transcripts; Form 4506 requests copies of returns. The IRS disaster victim FAQs address other federal tax questions that may arise during recovery.
Give every recovery expense a clear record
Track cleanup, temporary space, repairs, replacement purchases, and extra labor separately from routine spending. Save itemized invoices and proof of payment. Note whether an expense relates to a damaged asset, an insurance claim, or keeping operations open.
Don't classify every storm cost as an ordinary repair in your books. Replacement equipment, building work, and insurance proceeds may need different accounting or tax treatment. A bookkeeper or tax professional should review complex entries before you change a prior-period report.
Rework cash flow as the business reopens
Your pre-storm forecast is a starting point, not a schedule you must follow. Update it as soon as you know your actual operating limits.
Prioritize the next payment cycle
Confirm how much cash remains accessible, which invoices customers still owe, and what payments will clear soon. Then check the next payroll date, rent, taxes, utilities, and critical suppliers. If a bank feed is delayed, use bank records to confirm cleared transactions before relying on the accounting balance.
Communicate early with employees and vendors when schedules change. If payroll processing is disrupted, coordinate with your provider on a workable method and preserve hours, wage, and payment records. Keep withholding and employer tax obligations visible in the cash plan.
Separate help received from money expected
Record insurance advances, reimbursements, borrowed funds, and owner contributions according to their actual terms. A submitted claim or loan application isn't cash on hand. Until you receive a decision, model the forecast without that money.
Revisit collections weekly as customers recover. A Fort Myers service business may be ready to work while clients still face closures of their own. That gap matters when deciding which purchases can wait and when to restart normal spending.
Check tax deadlines and loss treatment for the specific event
Disaster tax rules depend on the event, your location, and the type of return or payment. Review current notices before changing a filing calendar.
Verify relief rather than assuming an extension
The IRS publishes tax relief in disaster situations by event and affected area. Check whether Lee County is included, which taxpayers qualify, and exactly which deadlines move. Don't assume a hurricane warning alone postpones a deposit, return, or estimated payment.
Check Florida Department of Revenue announcements separately for state taxes. If you file sales tax or employ workers, keep those due dates on your recovery calendar until you confirm that applicable relief changes them. Federal and Florida notices may cover different obligations.
Keep the evidence behind a possible loss claim
Tax treatment isn't the same as an insurance claim calculation. Preserve purchase records, improvement costs, photos, insurance correspondence, and recovery payments so your preparer can evaluate the loss. The IRS explains the rules in its guidance on casualty, disaster, and theft losses.
Don't book a tax benefit before your accountant reviews the facts. The property's use, its tax basis, insurance proceeds, and the applicable disaster rules all matter. Prior-year changes or tax adjustments deserve particular care.
Verify financial assistance before building a plan around it
SBA disaster loans depend on a qualifying declaration that covers the location and applicant. Check the SBA's current disaster listing for Lee County, application deadlines, permitted uses, and required documents. An application doesn't establish eligibility or approval.
Local assistance can be narrower than its name suggests. For example, published terms for the Fort Myers CRA's Downtown Storm Mitigation and Resiliency Grant Program describe reimbursement of up to 75% of eligible costs, capped at $100,000 per business. Check whether the program is open, whether your property qualifies, and whether approval must come before spending. Its listed exclusions include general repairs and operating costs.
Use your reconciled statements, damage inventory, and estimates to evaluate any option. Don't commit expected assistance to payroll or repairs until you understand the terms and have a confirmed source of funds.
Key Takeaways
- Before hurricane season, reconcile accounts, save off-site records, photograph assets, and review insurance terms.
- Keep a weekly cash forecast that shows essential bills against money available now, not hoped-for reimbursements.
- After damage, put safety first, document conditions, and retain separate records for claims and recovery expenses.
- Confirm tax relief and assistance against the notice or program for your specific event and location.
Frequently Asked Questions
What if my Fort Myers business lost its bookkeeping records?
Start with bank and credit card statements, payment processor reports, customer invoices, supplier records, and payroll provider reports. Request missing tax records when needed, then rebuild transactions in date order. Reconcile the result to actual account balances before using it for a claim, loan application, or return.
Should I keep paying employees if the business closes temporarily?
Your obligations depend on the employees' work, pay arrangements, and applicable law. Document hours worked and payments made, and speak with your payroll provider or qualified adviser about your circumstances. Keep payroll dates in the cash forecast even while you confirm what is owed.
Does a federal disaster declaration automatically extend every tax deadline?
No. An IRS relief notice identifies the affected area, eligible taxpayers, and postponed deadlines. Some obligations may remain due unless the notice addresses them. Check the notice for your event and confirm state deadlines separately before changing your payment plan.
Keep the financial picture usable
A storm may interrupt sales overnight. Current records and a realistic cash forecast give you a way to make the next decision without relying on memory or an unapproved claim.
Prepare the file before hurricane season, then update it as facts change after a loss. If your books need rebuilding or your tax treatment is uncertain, contact Meghan Sophia Tax & Accounting for help reviewing the numbers.